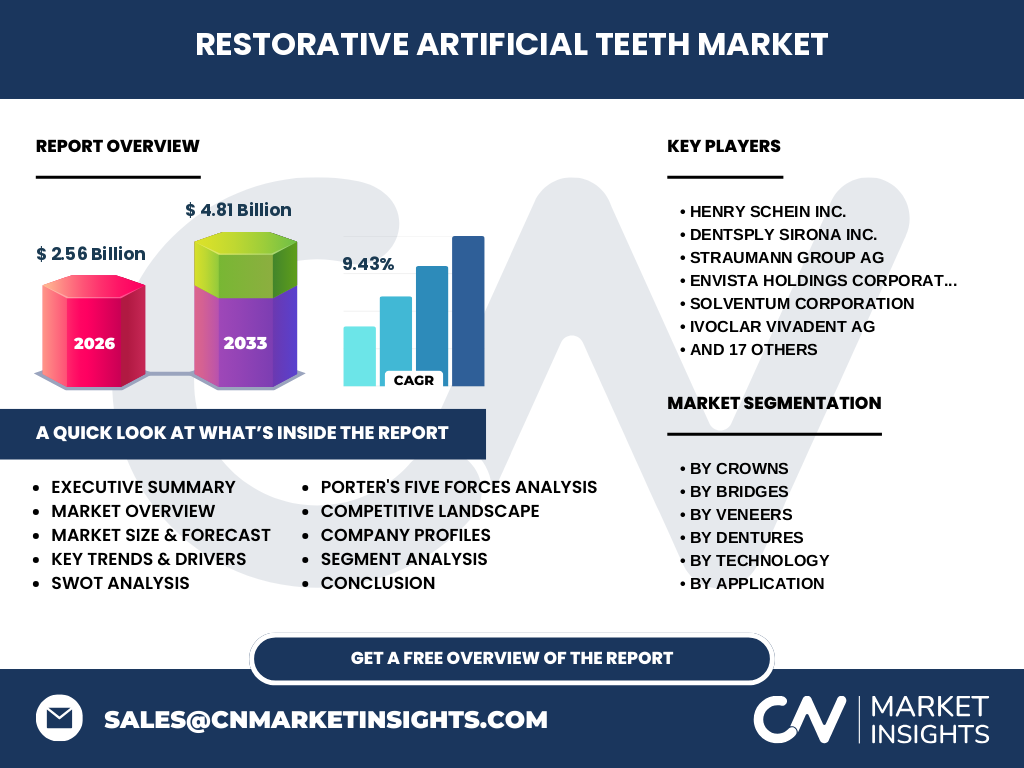
Market overview of the Restorative Artificial Teeth Market
Our analysis indicates the Restorative Artificial Teeth Market is valued at $2.56 Billion in 2026, driven by rising edentulism rates and technological advancements in ceramic and zirconia materials. Regulatory compliance with FDA and CE standards governs manufacturing processes across global supply chains involving titanium and acrylic raw materials.
Key market drivers, restraints, challenges, and opportunities shaping the sector
The market thrives on aging populations and digital dentistry adoption. However, strict biocompatibility protocols from agencies like ISO present regulatory hurdles. Opportunities lie in 3D printed restorations and expanding dental clinics across emerging economies, offsetting high equipment acquisition costs for independent practitioners.
Emerging trends and growth patterns
The industry is shifting toward chairside Computer Aided Design Or Computer Aided Manufacturing Restorations. Patients increasingly demand aesthetic perfection via Porcelain Veneers and Zirconia Crowns, prompting manufacturers like Dentsply Sirona and Straumann Group to accelerate R&D in digital workflows.
COVID-19 impact analysis and recovery trajectory
The pandemic caused elective procedure shutdowns, temporarily depressing demand for fixed prosthetics and complete dentures. Post-COVID recovery has been robust, fueled by safety protocols, pent-up patient demand, and accelerated integration of tele-dentistry and digital supply platforms.
Competitive landscape and strategic dynamics
Industry leadership is consolidated among innovators like Henry Schein Inc., Ivoclar Vivadent AG, and Glidewell Laboratories. Competition centers on material durability, digital ecosystem integration, and direct distribution channels to dental laboratories and clinical networks.
Executive summary of key findings
The data suggests exceptional momentum, projecting the market to reach $4.81 Billion by 2033 at a CAGR of 9.43% from 2027. Strategic consolidation and material innovations in titanium dental implants and ceramic inlays are reshaping clinical standards globally.
Market forecast from 2027 to 2033
Projected growth from $2.56 Billion in 2026 to $4.81 Billion by 2033 reflects a steady 9.43% CAGR. This expansion is propelled by rising disposable incomes and expanding insurance coverage for fixed and removable prosthetics across key international territories.
Segmentation analysis across core product lines
Segmentation spans Crowns (Porcelain, Zirconia, Metal), Bridges (Traditional, Implant-Supported), Veneers (Composite, Ultra Thin), and Dentures (Complete, Partial). Each segment plays a vital role in addressing specific patient clinical requirements, material preferences, and budgetary constraints.
Regional market analysis and geographic distribution
North America and Europe dominate consumption due to advanced healthcare infrastructure and high adoption of digital dentistry solutions. Meanwhile, Asia-Pacific represents the fastest-growing regional market, driven by expanding dental tourism and rising healthcare expenditures in urban centers.
In-depth regional review of key markets
In North America, stringent FDA oversight ensures high compliance for Endosteal Implants and Zygomatic Implants. Conversely, the Asia-Pacific region benefits from lower manufacturing costs for acrylic and metal alloy prosthetics, attracting substantial investments from regional players like Osstem Implant Co. Ltd.
Company profiles and strategic positioning
Market giants such as Envista Holdings Corporation, Solventum Corporation, and Mitsui Chemicals Inc. leverage extensive distribution networks. Companies like Planmeca Oy focus on diagnostic hardware integration, while ZimVie Inc. specializes in advanced dental implant technologies.
Porter's Five Forces analysis
Supplier power remains moderate due to specialized raw material sourcing for zirconia and titanium. Buyer power is high among large dental laboratory chains, while threat of substitutes is mitigated by continuous aesthetic and functional improvements in artificial teeth prosthetics.
SWOT analysis of the industry
Strengths include high material biocompatibility and advanced CAD/CAM precision. Weaknesses involve high capital expenditures for 3D printers. Opportunities emerge in mini dental implants, while threats include regulatory delays and counterfeit material imports affecting patient safety.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material extraction of titanium, ceramics, and composite resins, processed by chemical manufacturers like Kuraray Noritake Dental Inc. Products flow through dental distributors and online supply platforms to hospitals and private dental clinics.
Investment insights and high-potential areas
High-potential investment avenues target Three Dimensional Printed Restorations and digital dentistry solutions. Venture capital and corporate M&A activity favor firms demonstrating proprietary biomaterial formulations and seamless chairside workflow integrations.
Conclusion and key takeaways
The Restorative Artificial Teeth Market offers strong compounding returns anchored by technological innovation and demographic aging. Stakeholders prioritizing digital integration and high-end aesthetic materials like zirconia crowns will capture outsized market share through 2033.
Research methodology and data triangulation
Our research triangulates data by synthesizing customs trade registry statistics, primary interviews with key opinion leaders across Straumann Group and Dentsply Sirona, and macroeconomic indicators published by global dental health federations to establish robust baseline estimates.
Scope of the report and coverage parameters
This report covers global market dynamics from 2026 to 2033, evaluating product categories including Inlays And Onlays, Bridges, and Veneers. Limitations exclude informal grey-market dental manufacturing and non-certified artisanal dental laboratories operating outside regulatory frameworks.
Recent developments, partnerships, and strategic moves
Recent industry moves highlight strategic acquisitions and product rollouts by Amann Girrbach AG and VOCO GmbH, focusing on high-speed milling materials and bioactive composite resins. Collaborations between software developers and implant manufacturers are streamlining digital surgical planning.